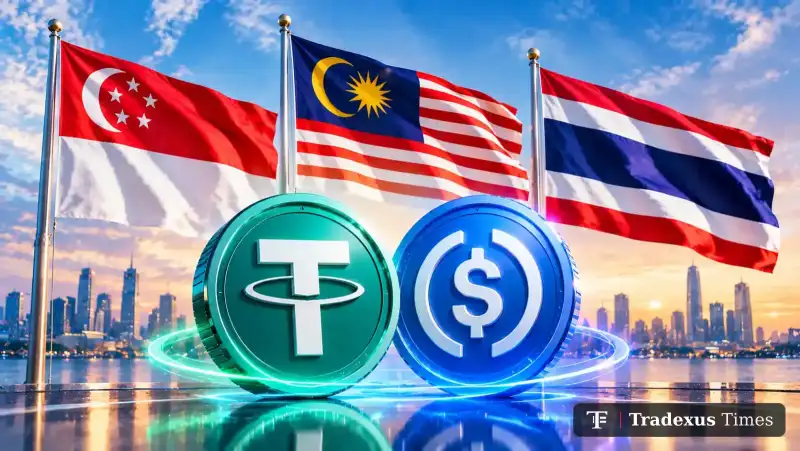
Singapore is expanding its BLOOM initiative to include Malaysia and Thailand, bringing three Southeast Asian central banks together to develop more efficient cross-border settlement systems using regulated stablecoins and tokenized bank deposits. The initiative aims to address one of the biggest challenges in international digital payments: enabling different financial networks to work together while maintaining regulatory safeguards.
The Monetary Authority of Singapore announced on October 23 that Bank Negara Malaysia and the Bank of Thailand had joined BLOOM as policymaker members. The collaboration will focus on cross-border settlement, interoperability between digital money networks, and programmable compliance controls, including identity verification, sanctions screening, and transaction restrictions. Rather than introducing a shared stablecoin or common licensing system, the initiative is designed to develop practical frameworks that financial institutions can use across different jurisdictions.

The expansion also brings major financial and payment companies into the broader effort, including Ripple, Mastercard, Maybank, Visa, Airwallex, Nium, ShopeePay, and the World Bank Group. Existing participants include Circle, Coinbase, J.P. Morgan, DBS, Anchorage Digital, and Standard Chartered. Their involvement could help establish commercial and technical connections between traditional banking infrastructure and emerging digital money networks.
For Ripple, participation builds on its existing work exploring how RLUSD and blockchain-based settlement could support trade finance transactions. However, the expanded initiative does not mean that Malaysia or Thailand has approved RLUSD for domestic payments, nor has Singapore announced the token as a required settlement asset. Circle, the issuer of USDC, is also involved in the wider initiative, but no new USDC settlement corridor or regional regulatory approval was announced.
BLOOM is also building on earlier experiments involving regulated dollar- and euro-backed stablecoins. A pilot involving Visa and Nium is examining how stablecoin settlement could support international payments outside conventional banking hours, including weekends and public holidays. If these arrangements prove practical, they could help financial institutions reduce delays associated with traditional cross-border settlement processes.
Malaysia is pursuing its own digital money experiments through Bank Negara Malaysia’s Digital Asset Innovation Hub. The central bank has announced controlled initiatives involving ringgit-denominated stablecoins and tokenized deposits for domestic and international wholesale payments. The work is expected to inform future policy decisions, including how tokenized financial assets could be settled and whether they could connect with wholesale central bank digital currency research.
Thailand is moving forward with a separate regulatory process for baht-backed stablecoins. Its central bank opened a public consultation on October 20 covering proposed requirements for issuers and wallet providers, including reserve backing, redemption safeguards, transaction monitoring, and cybersecurity. The proposals treat stablecoins as a potential complement to existing payment systems while addressing risks to financial stability and consumers.
These national initiatives highlight why coordination matters. A stablecoin that meets the requirements of one country may not automatically qualify for use in another. Different rules governing reserves, redemption, customer verification, and transaction monitoring can create barriers even when the underlying blockchain technology is compatible. BLOOM aims to explore how common implementation frameworks and technical connections could reduce the need for institutions to negotiate separate arrangements with every international counterparty.
The World Bank Group’s participation adds another dimension, bringing experience in payment modernization and financial inclusion. However, the project has not yet announced a launch date for a three-country settlement service, expected transaction volumes, or a final timetable for adopting common rules. The central banks will retain responsibility for their respective regulatory decisions as the participating institutions work on implementation frameworks.
For the digital asset industry, the initiative represents a further step toward connecting regulated stablecoins and tokenized deposits with established financial infrastructure. If the participating institutions can establish compatible standards and workable settlement arrangements, cross-border payments could become more flexible and efficient. For now, the key milestone is the development of the framework itself, rather than the launch of a unified regional payment network.