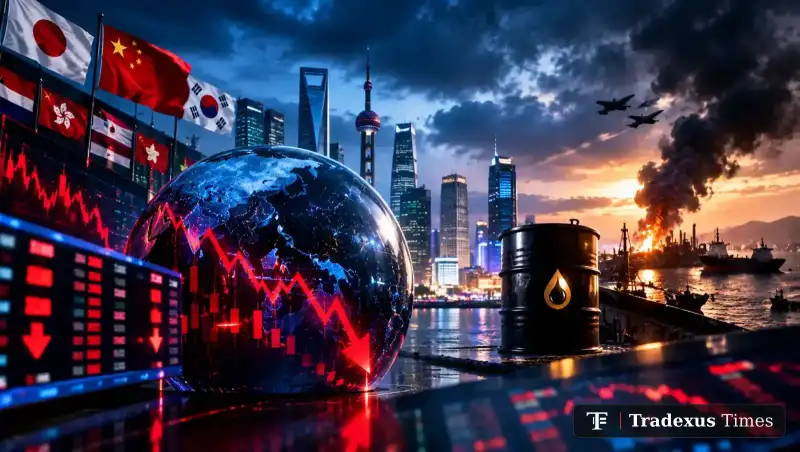
Asian markets came under renewed pressure on Thursday as investors weighed strong technology earnings against concerns over artificial intelligence spending, rising geopolitical risks in the Gulf and uncertainty surrounding the next Federal Reserve decision. Despite an overnight advance on Wall Street, optimism struggled to carry over into Asian trading, leaving regional equities vulnerable to another weekly decline.
MSCI’s broadest index of Asia-Pacific shares outside Japan slipped 0.2%, putting it on course for a fourth consecutive week of losses. Japan’s Nikkei fell 0.4% after giving up earlier gains, while South Korean shares declined by more than 1%. U.S. equity futures also weakened, indicating that investors remained cautious even after several major companies delivered encouraging financial results.

Technology earnings provided some support to sentiment. SpaceX reported its first profit as a publicly traded company, Meta posted third-quarter revenue above expectations, and AI server manufacturer Super Micro projected stronger-than-expected quarterly revenue and profit margins. These results offered evidence that demand for AI infrastructure remains strong, but they did little to resolve questions about whether the enormous investments being made in the sector will generate sufficient long-term returns.
Meta’s plan to issue non-voting Class C common stock added to investor scrutiny of its financing strategy and AI spending. As earnings season gathers pace, markets are increasingly focused not only on revenue growth but also on capital expenditure, profitability and the ability of technology companies to turn AI demand into sustainable earnings.
Geopolitical uncertainty is adding another layer of pressure. Brent crude rose 1.1% to around $110 a barrel, approaching a five-month high amid concerns over regional security and potential disruptions to energy supplies. Reports of Houthi attacks and renewed military contingency planning involving Iran have heightened attention to the risk of a broader escalation. Any sustained increase in oil prices could intensify inflationary pressures and complicate central-bank decisions.
Bond markets reflected a complicated outlook. The U.S. 10-year Treasury yield fell by 4.2 basis points to approximately 5.11%, while the 30-year yield reached a one-week low near 5.40%. Lower yields can sometimes support equities by easing financial conditions, but in this environment they also reflect uncertainty about economic growth, inflation and geopolitical developments. Investors remain sensitive to the possibility that energy-driven price pressures could limit the room for monetary easing.
Currency movements were relatively restrained. The dollar index eased to 102.2, while the euro traded near $1.1231. The yen held around 158.13 per dollar after Bank of Japan Deputy Governor Ryozo Himino signalled openness to higher borrowing costs. South Korea’s won was little changed after the Bank of Korea kept its benchmark interest rate at 3.00%.
Precious metals and cryptocurrencies also showed signs of caution. Gold edged lower to around $4,115.50 an ounce, while Bitcoin slipped 0.4% to approximately $84,284 and Ether fell 0.6% to around $2,476. The moves suggest that enthusiasm surrounding technology earnings has not been enough to offset broader uncertainty across financial markets.
The immediate outlook will depend on whether corporate earnings can sustain confidence in AI-related growth while geopolitical risks and energy prices remain elevated. Investors are also watching the Federal Reserve’s upcoming policy decision and the approaching U.S. midterm elections. Until greater clarity emerges, markets may continue to react sharply to new earnings reports, oil-price movements and developments in the Gulf.