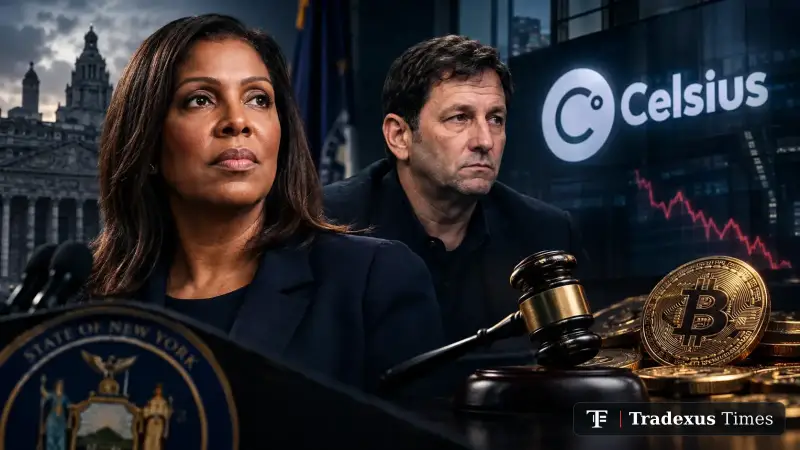
New York Attorney General Letitia James said the state secured a settlement requiring former Celsius CEO Alex Mashinsky to forfeit up to $35 million under specified conditions and permanently barring him from working in the securities, commodities or cryptocurrency industries. The agreement follows a lawsuit filed by James in 2023, which accused Mashinsky of misleading hundreds of thousands of investors about the safety of their Celsius deposits, including more than 26,000 New Yorkers.
The settlement establishes financial penalties tied to two separate conditions. Mashinsky must pay New York $25 million if he does not forfeit $10 million in ill-gotten gains to the federal government, while a further $10 million becomes payable if he fails to serve his full prison sentence, according to the attorney general's office. The structure links the state's financial recovery to forfeiture and sentence-completion requirements rather than representing an unconditional cash payment of the full amount.

Mashinsky is serving a 12-year federal prison sentence after pleading guilty to securities and commodities fraud. He was also permanently barred from commodities activity by the Commodity Futures Trading Commission in June, adding to the restrictions on his ability to participate in financial markets. The New York agreement extends the consequences of the Celsius collapse by imposing a separate state-level industry ban and conditional financial obligations.
The case stems from Celsius's collapse in 2022. The crypto lending platform froze customer withdrawals in June before filing for bankruptcy the following month. James alleged that Mashinsky promoted Celsius as safer than a bank while the company deployed customer assets in risky strategies and concealed losses. Those allegations formed the basis of the state's enforcement action, while Mashinsky's guilty plea resulted in his federal prison sentence.
The financial fallout has extended well beyond the legal penalties imposed on the former CEO. According to James, Celsius customers and creditors had received more than $3.4 billion through bankruptcy proceedings as of August. The company had planned to distribute roughly $3 billion in cryptocurrency and cash when it emerged from bankruptcy in 2024, using Coinbase and PayPal to facilitate payments.
For the digital-asset industry, the settlement reinforces the potential personal and financial consequences for executives accused of misrepresenting the risks associated with crypto lending products. Celsius offered customers exposure to digital assets through a platform that ultimately suspended withdrawals and entered bankruptcy, leaving customer recovery dependent on the restructuring process. The distinction between amounts recovered through bankruptcy and penalties imposed on executives remains important when assessing the extent of investor losses and restitution.
The settlement also illustrates how enforcement can extend across multiple jurisdictions and regulatory bodies. New York's restrictions operate alongside the federal criminal sentence and the CFTC's commodities ban, narrowing Mashinsky's ability to return to regulated financial activity. For crypto businesses, the case underscores the importance of accurately describing how customer assets are managed, the risks associated with lending strategies and the protections available to depositors.
The next point to watch is how the settlement's conditional payments and forfeiture requirements are implemented, alongside continuing distributions to Celsius creditors. The announced maximum should not be interpreted as money already recovered by New York, because the payment obligations depend on the specified conditions. The broader implications for the sector will also depend on how regulators apply existing securities, commodities and consumer-protection rules to digital-asset platforms and their executives.