U.S. financial markets are heading into a particularly important week from November 2 to 6, 2026, as several major political, corporate and economic events converge. The U.S. midterm elections, earnings reports from leading technology companies and the release of October employment figures could all influence investor sentiment, market volatility and expectations for the direction of the U.S. economy.
The week begins on Monday, November 2, with earnings reports from Apple and Palantir. Investors will be watching the companies' financial performance, management outlook and commentary on business growth. Apple's results could provide insight into consumer demand and the broader technology sector, while Palantir's performance may attract attention amid continued interest in artificial intelligence and enterprise software.

Tuesday, November 3, brings another major technology earnings release from AMD, alongside the U.S. midterm elections. AMD's results and forward guidance could offer important signals about demand for semiconductors, data centers and AI infrastructure. At the same time, the election results could reshape the balance of power in Congress, potentially influencing the legislative environment for businesses and financial markets.
The political implications extend beyond traditional industries. Changes in congressional control could affect future debates surrounding artificial intelligence regulation, banking oversight and cryptocurrency legislation. The outcome may also influence broader U.S. policy discussions, including foreign affairs and the ongoing Iran conflict, although the extent of any policy changes will depend on subsequent political decisions.
On Wednesday, November 4, Qualcomm is scheduled to report earnings. Its results could provide additional insight into the semiconductor industry, smartphone demand and developments in connected technologies. Together, the reports from AMD and Qualcomm will give investors a broader picture of conditions across the chip sector, particularly as demand for AI-related infrastructure continues to attract market attention.
Friday, November 6, will bring one of the week's most important economic releases: the U.S. Nonfarm Payrolls report for October. The employment figures will help investors assess the strength of the labor market and whether economic activity is continuing to expand or showing signs of weakness. Wage growth and employment trends are also important because they can influence inflation expectations and the Federal Reserve's interest-rate decisions.
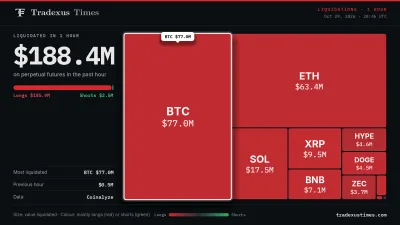
For equity markets, the combination of election uncertainty, corporate earnings and employment data creates several potential catalysts for sharp price movements. Technology stocks could react to company guidance, while broader market sentiment may shift as investors evaluate the political and economic outlook. Cryptocurrency markets could also remain sensitive to developments in U.S. regulatory policy, particularly if the election results change the direction of congressional discussions on digital assets.
With several high-impact events concentrated into just five trading days, investors will have to assess both company-specific developments and broader macroeconomic signals. The key question is whether corporate earnings and economic data can support market confidence while political uncertainty creates additional volatility.