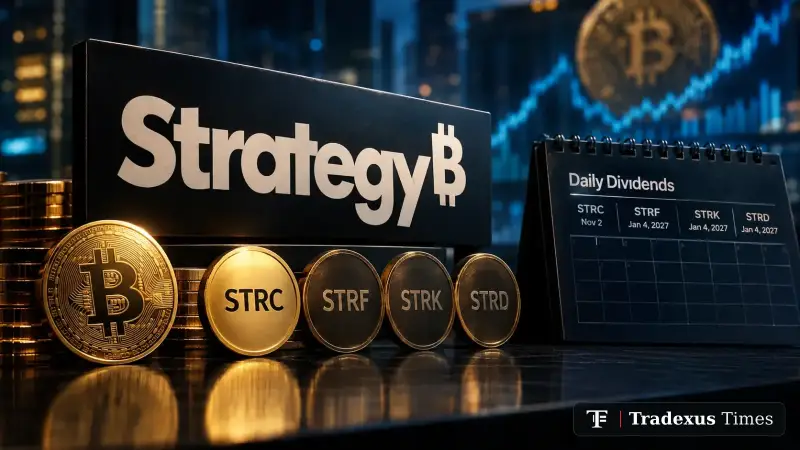
Strategy shareholders have approved amendments to the terms of the company’s preferred stock, paving the way for daily dividend accruals and payments across all four preferred series. Preliminary results released Wednesday indicate that the changes will shift distributions away from semi-monthly or quarterly schedules without changing the stated annual dividend rates.
The revised structure affects STRC, STRF, STRK and STRD, with implementation staggered across the preferred stock lineup. Strategy expects daily payments for STRC to begin on November 2, while STRF, STRK and STRD are scheduled to transition to daily distributions on January 4, 2027.

The change focuses on the timing of income rather than the underlying annual dividend rates. Under the amended terms, dividends will accrue every day, including weekends and holidays, reducing the interval between when income is earned and when investors receive payment. The distinction is important for preferred shareholders who prioritize recurring cash distributions, although daily payments do not independently increase the stated annual yield.
Strategy’s preferred securities carry annual dividend rates ranging from 8% to 12%. STRC has a variable rate currently set at 12%, while STRF, STRK and STRD carry fixed dividend rates. STRK also offers a conversion feature that allows holders to exchange their preferred shares for Strategy common stock, giving the security an additional equity-linked characteristic beyond its income component.
For investors, the operational appeal of daily distributions lies in cash-flow frequency. More frequent payments could provide greater flexibility in managing proceeds and make the securities more attractive to investors seeking regular income. However, the economic value of that change depends on factors beyond payment timing, including each security’s dividend terms, market price and the risks associated with the issuer.
Strategy has said the daily-payment model is intended to improve liquidity and contribute to greater stability in the trading prices of its preferred shares. Those objectives remain to be demonstrated in market trading. A more frequent distribution schedule may improve the investor experience, but it does not by itself guarantee tighter bid-ask spreads, deeper market liquidity or lower price volatility.
The amendment also reflects a broader financing approach among publicly traded companies holding Bitcoin on their balance sheets. Preferred securities allow companies to raise capital through instruments with defined dividend structures, while potentially supporting corporate funding strategies that differ from issuing common equity or relying exclusively on debt.
Strive has already introduced a similar model. The company began daily cash dividends on its SATA preferred stock in June and subsequently launched SATS, a second preferred security carrying a fixed annual dividend rate of 15%. Daily SATS payments are scheduled to begin on November 9, subject to a formal dividend declaration.
Strive’s capital-raising activity illustrates how preferred securities can connect investor income requirements with corporate financing plans. The company closed a $630 million SATS offering on October 20, selling seven million shares at $90 each. Strive said proceeds could support Bitcoin purchases and other corporate purposes, but it did not disclose the amount earmarked for cryptocurrency acquisitions.
The scale of the two companies’ Bitcoin holdings provides additional context. BitcoinTreasuries.net data identifies Strategy as the largest publicly traded corporate Bitcoin holder, with 848,517 BTC, while Strive ranks fourth with 43,000 BTC. Their different balance-sheet sizes show that daily dividend structures are not confined to companies with comparable Bitcoin portfolios, even as both firms use preferred securities as part of their financing strategies.
For the broader market, the significance of these changes lies in the interaction between income-oriented securities and corporate Bitcoin exposure. More frequent dividends could widen the appeal of preferred shares among investors who value predictable payment schedules. If that translates into sustained demand, it could support companies’ ability to use preferred stock as a financing instrument. The approval itself, however, does not establish that investor demand or secondary-market liquidity will improve.
The next test will be the implementation of Strategy’s revised schedule. The initial rollout for STRC on November 2 will provide the first opportunity to assess how the daily structure operates in practice, followed by the transition of STRF, STRK and STRD in January. Trading behavior around those changes may help indicate whether more frequent distributions influence demand, price stability or liquidity in the preferred securities.
Investors will also need to distinguish between dividend frequency and dividend economics. Strategy’s amendments change the timing of distributions, not the stated annual rates. The variable rate on STRC adds a separate consideration because its dividend can change, unlike the fixed-rate structures of the other three series.
Ultimately, the effectiveness of daily dividends will depend on whether the revised payment schedule delivers practical benefits without changing the underlying risk profile of the securities. Strategy’s rollout, alongside Strive’s existing and planned structures, will offer a clearer view of how daily distributions fit into the evolving financing models of publicly traded Bitcoin treasury companies.