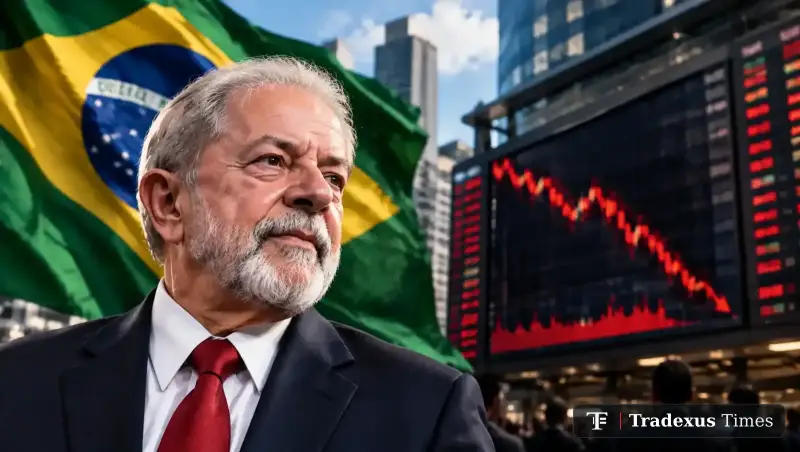
Brazilian financial markets came under heavy selling pressure after President Luiz Inácio Lula da Silva secured a surprise victory over right-wing challenger Flávio Bolsonaro in the country’s presidential runoff election. The result reversed an earlier rally in Brazilian assets and renewed investor concerns about fiscal policy, interest rates, and the country’s economic outlook.
The iShares MSCI Brazil ETF (EWZ), which tracks Brazilian equities, fell as much as 25% in premarket trading on Monday. If sustained through the session, the decline would represent its largest single-day drop since the fund began trading in 2000, surpassing its previous record fall of approximately 23% during the market turmoil of March 2020.

Individual stocks also faced substantial losses. Shares of Petrobras, Brazil’s majority state-owned energy company, dropped around 20%, while Nu Holdings, the parent company of digital banking group Nubank, fell approximately 26% in early trading. The sharp moves reflected the immediate reassessment of Brazilian assets following an election outcome that differed from market expectations.
Earlier in the month, Brazilian equities had rallied after Flávio Bolsonaro delivered a stronger-than-expected performance in the first round of voting. Investors had viewed his candidacy as potentially signaling a shift toward more business-oriented policies and tighter fiscal management. The subsequent victory by Lula overturned those expectations and prompted a rapid reversal in positioning.
The election result also highlighted the risks of relying too heavily on polling and prediction-market expectations when assessing political outcomes. Despite indications that Bolsonaro held a narrow lead in some polls and was favored in certain prediction markets, the final result produced a markedly different reaction across financial assets.
For investors, the central concern now is Brazil’s fiscal trajectory and its implications for monetary policy. Uncertainty over government spending, debt sustainability, and the credibility of future budget measures could keep bond yields elevated and put pressure on equities, particularly if investors demand higher returns to compensate for perceived fiscal risks.
The outlook for interest rates is another key factor. Concerns about fiscal discipline could limit the central bank’s room to reduce borrowing costs, potentially delaying or slowing an expected easing cycle. Higher interest rates can weigh on corporate valuations, increase financing costs, and reduce the appeal of risk-sensitive assets.
However, the initial market reaction does not necessarily determine the longer-term performance of Brazilian investments. The direction of markets will depend on the government’s economic policies, fiscal decisions, inflation trends, and the central bank’s response. Investors will be watching for concrete policy signals as the administration’s next steps become clearer.
For now, the sell-off underscores how closely Brazilian asset prices are tied to expectations surrounding fiscal management and economic policy. The scale and persistence of the market reaction will depend on whether the government can provide investors with greater clarity about its fiscal priorities and the country’s medium-term economic direction.