French government bond yields edged lower on Tuesday but remained close to levels last seen more than two decades ago, as renewed protest threats and political uncertainty kept investors cautious about the country’s fiscal outlook. The modest retreat followed the sharpest daily rise in French borrowing costs in nearly a month, highlighting the volatility surrounding the country’s debt market.
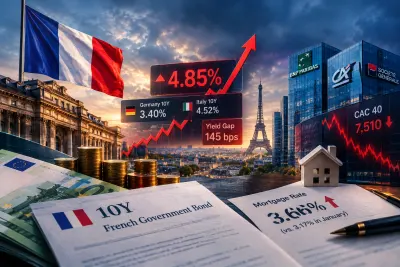
France’s 10-year OAT yield was last down 3 basis points at 4.88%, after reaching an intraday high of 4.9877%. That peak approached the early October high of 4.9937%, the highest level recorded since July 2002. Although yields eased during the European afternoon, the move offered limited relief as investors continued to assess the economic and political consequences of further unrest.

The gap between French and German 10-year government bond yields also widened, reaching around 150 basis points after increasing by approximately 2.5 basis points. The spread, which measures the additional yield investors demand to hold French debt rather than German benchmark bonds, reflects the relative pressure facing France. In early October, the gap reached 158.67 basis points, its widest level since November 2011. By contrast, Italy’s spread over Germany narrowed by 1.57 basis points to 109.5 basis points.
The latest market moves came as French protest groups called for further demonstrations following unrest over the weekend. Analysts warned that renewed disruption could add pressure to an economy already dealing with tighter financial conditions, political uncertainty and restrictive fiscal policy. Goldman Sachs strategists said the direct economic impact could remain limited in the near term, but further disruption would create another headwind for growth.
The political implications are also attracting attention. A poll published last week showed far-right leader Marine Le Pen and hard-left figure Jean-Luc Mélenchon extending their leads over other potential candidates ahead of the weekend’s events. Analysts have raised concerns about the implications for efforts to reduce France’s budget deficit, arguing that any government could face considerable public resistance to spending cuts and structural reforms.
Benjamin Schroeder, senior rates strategist at ING, said the protests underscored the difficulty any administration would face in implementing the reforms and savings needed to improve public finances. He also noted that the political fallout could benefit right-wing and centrist candidates, while Mélenchon’s prospects may have weakened because of perceptions surrounding his policy proposals.
Elsewhere in the eurozone, German government bond yields moved lower, with the benchmark 10-year Bund yield falling 7 basis points to 3.385%. Germany’s two-year yield, which is more sensitive to expectations for monetary policy, declined 5 basis points to 3.045%. Both moves came as investors continued to weigh the outlook for European Central Bank interest rates against persistent energy-price pressures.
Despite the latest decline in yields, analysts said it could be difficult to substantially reduce market expectations for further ECB rate increases while energy prices remain elevated. The trajectory of gas prices through the winter is likely to be an important factor in shaping inflation expectations and monetary policy forecasts.
For France, the combination of high borrowing costs, political uncertainty and pressure to rein in public spending remains a concern for investors. Tuesday’s retreat in yields may offer temporary relief, but the country’s elevated borrowing premium over Germany suggests that markets continue to differentiate French debt from the eurozone benchmark. Further protests, developments in fiscal policy and changes in energy prices are likely to remain key drivers of bond-market sentiment.