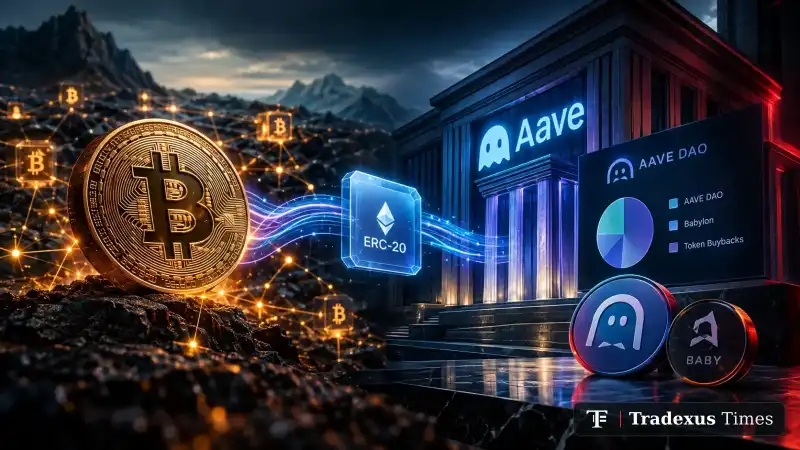
Babylon Labs has proposed integrating native Bitcoin as collateral into Aave V4, potentially allowing Bitcoin holders to borrow stablecoins without transferring their BTC off the Bitcoin blockchain. The proposal, submitted to Aave's governance forum on October 14, 2026, introduces a lending structure built around Babylon's Trustless Bitcoin Vaults and a tiered revenue-sharing agreement with the Aave DAO. The initiative has reached the Aave Request for Final Comments (ARFC) stage but remains subject to risk assessments and governance approval.
The proposal, titled "Onboard Native BTC as Collateral to Aave V4 via Babylon Trustless Bitcoin Vaults," follows a successful preliminary temperature check. Its initial application focuses on stablecoin borrowing against native Bitcoin, addressing a longstanding technical limitation in decentralized lending: using Bitcoin as collateral without relying on conventional wrapped assets, custodians or cross-chain transfers. If approved, the integration could expand the types of collateral supported by Aave while introducing a new source of protocol revenue.
In this story
2 assets

Unlike conventional Bitcoin-backed DeFi lending arrangements, Babylon's architecture keeps the underlying BTC locked in Taproot-based unspent transaction outputs (UTXOs) on the Bitcoin network. These outputs contain programmable spending conditions that govern how and when the Bitcoin can be released. The collateral therefore remains on Bitcoin's blockchain rather than being transferred to Ethereum or deposited with a centralized custodian.
To make the collateral recognizable within Aave V4, the system creates an ERC-20 representation on Ethereum with eight decimal places. The token is minted when a Bitcoin vault becomes active and burned when the corresponding position closes. Transfers are restricted to the integration's designated smart contracts, while the outstanding token supply must remain equal to the Bitcoin committed to active vault positions. This design establishes an accounting representation of native BTC rather than introducing a freely tradable wrapped Bitcoin asset.
The integration would operate through two dedicated spokes within Aave V4's hub-and-spoke architecture, which separates liquidity management from individual lending markets. The Babylon Spoke would accept native Bitcoin exclusively as collateral, while the BTC Vault Swap Spoke would manage the settlement process following liquidations. Both would access liquidity through an Aave V4 hub, although the proposal does not identify the specific hub instance.
Several structural restrictions are defined in advance. Native Bitcoin would be eligible only as collateral and could not itself be borrowed through the Babylon Spoke. The liquidation fee would be fixed at zero, liquidators would not receive collateral shares, and the conventional target health factor mechanism would not apply. These restrictions reflect the operational differences between liquidating collateral held directly on Bitcoin and collateral represented by transferable assets on Ethereum.
The liquidation mechanism is a central feature of the proposal. Instead of transferring a percentage of a borrower's collateral to a liquidator, the system would seize exactly one Bitcoin vault during each liquidation. An eligible liquidator could then sell the seized vault to the BTC Vault Swap Spoke in exchange for wrapped Bitcoin (WBTC), priced against an oracle reference with an applied discount. Arbitrage participants would subsequently repay the WBTC obligation and redeem the underlying native Bitcoin.
The discount effectively replaces the conventional liquidation fee as compensation for liquidators. Its size, alongside a minimum arbitrage profit reserve and the designated fee recipient, would remain configurable. However, Babylon has not specified the numerical values for these settings.
Aave's risk service providers would be responsible for developing the relevant settings before final implementation.
The absence of these figures prevents a reliable assessment of borrowing capacity and liquidation sensitivity. Even with Bitcoin remaining on its native blockchain, borrowers would still face collateral liquidation risk if their positions breached the eventual thresholds. The system would also depend on the operation of its cross-chain representation, oracle pricing and vault settlement mechanisms. Keeping BTC outside a conventional bridge removes certain custody and transfer requirements but does not eliminate the economic or technical risks associated with collateralized lending.
Babylon's proposal arrives alongside other discussions concerning Aave's collateral framework. An October 15 ARFC addressed onboarding USAT, a US dollar token associated with Tether America, into Aave V3 Core and the V4 Core hub on Ethereum. Separate governance discussions covered a risk framework for tokenized equities on Aave V3 X Layer on October 14 and a CAPO SnapshotRatio adjustment on October 13. Together, these initiatives indicate an effort to broaden supported assets and refine risk management across Aave's lending infrastructure.
For native Bitcoin, the strategic opportunity is distinct. Allowing BTC to support stablecoin borrowing without leaving the Bitcoin blockchain could make Aave accessible to collateral that otherwise requires wrapping or custodial arrangements before entering Ethereum-based lending markets. Whether that translates into meaningful adoption would depend on borrowing terms, liquidation efficiency and the economic attractiveness of the integration relative to existing alternatives.
The proposal must still complete Aave's governance process. Following community feedback and risk-provider analysis, the next formal step would be a Snapshot vote, followed by an Aave Improvement Proposal (AIP) containing the full risk parameters for an on-chain vote. Until those approvals are secured, the proposed native Bitcoin lending market is not operational and its revenue arrangements remain prospective.
The immediate focus is therefore on the missing collateral parameters, the liquidation discount and the additional Babylon interest fee. Those details will determine whether the proposed structure can offer competitive borrowing conditions while maintaining adequate safeguards for Aave's liquidity providers. Governance approval would establish the path toward implementation, but actual lending activity and realized protocol revenue would ultimately determine the financial significance of Babylon's Bitcoin collateral initiative.
 PYTH